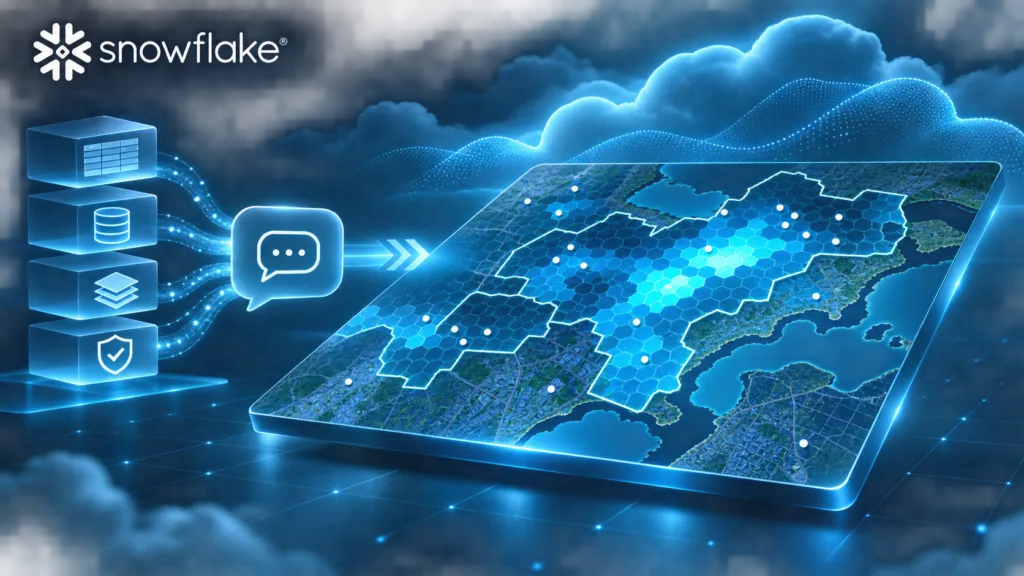
Snowflake has added geospatial maps to CoWork, its conversational enterprise-analysis environment. On the surface, the update looks modest: ask a question about stores, deliveries or sales territories, and the agent can return an interactive map instead of a conventional chart.
The strategic significance is larger. Snowflake is turning the map into a native output of the enterprise data agent.
The new capability, currently available as an open preview, supports latitude and longitude points, H3 hexagons and GeoJSON derived from Snowflake’s GEOGRAPHY and GEOMETRY data types. Users can ask follow-up questions to recolor results, switch to an H3 representation or revise the map without starting a separate mapping workflow.
Maps can also be saved as artifacts and shared. When a map is backed by a reusable query, refreshing it reruns that query under the viewer’s credentials. This is important because it places spatial output inside the same access-control model as the underlying enterprise data.
More than another chart type
Snowflake has created a dedicated MapSpec rather than treating maps as ordinary Vega-Lite charts. Through the Cortex Agents Run API, applications receive a specific response.map event alongside the existing table and chart responses.
That architectural choice suggests that maps are becoming a distinct object in Snowflake’s agent ecosystem rather than a decorative visualization added at the end of an analysis.
A regional manager could ask to map store revenue, compare delivery density by H3 cell and share the result without opening a desktop GIS or exporting data to another visualization tool. Query-backed maps remain connected to their source instead of becoming static screenshots.
For enterprise location intelligence, that removes significant interface friction. Many useful spatial questions are relatively straightforward but still require an analyst because business users do not know which tables, spatial functions or visualization tools to use.
What Snowflake has not built
The preview should not be confused with a complete GIS platform.
It supports a deliberately narrow set of map layers and basic color encoding. There is no manual map editor and no PNG export. Maps created from snapshot-only procedure or MCP results do not refresh from live data. Snowflake has not published evidence showing how the experience handles very large or complex geometries, invalid spatial data, multiple coordinate systems or costly analytical queries.
Most importantly, displaying spatial results is not the same as validating the analysis that produced them.
A persuasive map can still be based on a poor spatial join, an inappropriate H3 resolution or a misleading normalization method. Natural language lowers the interface barrier, but it does not remove the need for metadata, governed definitions and expert review.
Microsoft makes the same underlying point in its documentation for Copilot in Power BI: generative answers can be nondeterministic, and semantic models must be prepared for AI if organizations want consistent results.
The competitive landscape is moving quickly
Snowflake is entering a field where both GIS vendors and business-intelligence platforms are making maps conversational.
CARTO already connects its analytical tools to Snowflake agents through MCP. Its pitch goes beyond visualization: approved workflows for routing, isochrones, hotspot analysis and site selection can run inside the customer’s Snowflake warehouse. Those workflows are reusable and auditable instead of being recreated by the model for every question.
Snowflake’s native maps may reduce the need to open CARTO for a basic point, polygon or H3 visualization. They do not replace CARTO’s more advanced spatial analysis, scalable vector-tile maps or workflow tooling. In fact, the two products may become complementary: CoWork as the conversational entry point and CARTO as the specialist execution layer.
Esri is approaching the same market from the opposite direction. Its new agentic ArcGIS capabilities let external agents access spatial services through MCP while ArcGIS applications gain conversational interfaces of their own. Esri retains an advantage where organizations need authoritative GIS layers, advanced spatial analysis, editing and operational mapping.
Google Looker and Microsoft Power BI also combine conversational analysis with geographic visualizations. Their presence means Snowflake is competing not only with GIS platforms, but also with the established dashboard layer sitting above enterprise data.
The map is moving closer to the question
The most consequential part of Snowflake’s release is not the cartography. It is the collapsing distance between a business question, a governed query and a spatial result.
If the preview matures, more location questions will be answered inside the platforms where organizations already store and analyze their data. Specialist GIS will remain essential for difficult analysis and operational workflows, but it will no longer be the automatic starting point for every map.
That is the real shift. Location intelligence is becoming a standard behavior of enterprise AI, while the role of geospatial professionals moves toward building trusted data, reusable analytical methods and safeguards that ensure the agent’s attractive map is also the right one.

#GeoAI
Next article
ICEYE built its reputation by making synthetic aperture radar imagery faster, cheaper and more operationally useful. Now it wants to own something much heavier: access to orbit.
On 17 November, the Finnish Earth observation company announced an all-cash offer for Italian rocket and propulsion manufacturer Avio. The offer values Avio’s equity at approximately €2.05 billion, or €41 per share. That represents a 21.3% premium to Avio’s previous closing price and a 34.8% premium to its three-month volume-weighted average price.
If completed, the deal would combine one of Europe’s most important commercial SAR operators with the company behind the Vega C launcher, the future Vega E and major solid-propulsion components used by Ariane 6.
That is a much bigger strategic move than a conventional supplier acquisition.
From satellite operator to integrated space group
ICEYE currently controls a growing constellation, radar payload technology, ground systems and an intelligence-delivery platform. Avio would add launch vehicles, propulsion engineering, manufacturing infrastructure and deep relationships with European institutions.
The pitch is easy to understand. Europe wants more sovereign control over critical space infrastructure, while governments increasingly buy intelligence capabilities as complete systems rather than as individual images or satellites. A group able to provide radar spacecraft, data, analytics and launch services could bid for much larger national programs.
ICEYE has the financial momentum to attempt it. In June, the company announced a funding round exceeding €1 billion, including €450 million of new primary capital led by General Atlantic. It said 2025 revenue exceeded €250 million, EBITDA topped €100 million and its contracted backlog was above €1.5 billion. Those figures are company-reported, but they help explain how a private satellite company can contemplate buying a listed industrial group.
Avio brings a different kind of scale. Its 2025 backlog reached €2.17 billion, supported by European institutional launch programs and defense propulsion work.
The industrial logic is not automatic
Vertical integration sounds attractive, but ICEYE does not need a dedicated Vega launch for every radar satellite. Small SAR spacecraft are well suited to rideshare missions, and launch economics depend on cadence, reliability and customer mix, not simply common ownership.
Avio’s value also extends far beyond ICEYE’s constellation. Its future depends on European Space Agency programs, national defense customers and demand from third-party satellite operators. The combined company would therefore need to preserve Avio as a credible supplier to the wider market, including customers that may compete with ICEYE.
Competition is also intensifying. ArianeGroup remains central to Europe’s heavy-launch ecosystem, while Isar Aerospace, Rocket Factory Augsburg, PLD Space and MaiaSpace are pursuing new launch architectures. Brussels and ESA are actively funding a more competitive launcher market. ICEYE would be buying an incumbent platform at precisely the moment Europe is trying to diversify beyond incumbents.
Italy will decide what sovereignty means
The largest obstacle may be political rather than financial. Avio is a strategic Italian asset, and the transaction is subject to Italy’s golden-power review as well as approvals in France, the United Kingdom, the United States and under the EU Foreign Subsidies Regulation. The offer also requires acceptances representing at least 66.67% of Avio’s share capital.
Reuters reported that Rome is seeking security guarantees, continued Italian operations and a meaningful role for Leonardo, which is currently a major Avio shareholder. ICEYE has tried to anticipate that debate by pledging an additional €1 billion of investment in Italy over five years and up to 400 skilled jobs.
Those promises are strategically necessary, but they are not the same as binding long-term industrial outcomes. Governments will want clarity on intellectual property, sensitive defense programs, board control, production locations and priority access during a crisis.
The proposed acquisition captures Europe’s space dilemma in one transaction. The continent needs companies with enough scale to compete globally, but consolidation can also concentrate strategic capabilities in ways that make national governments nervous.
If ICEYE succeeds, it will no longer be best described as an Earth observation company. It will be attempting to become a European space prime, built around radar intelligence rather than around the traditional launcher or satellite-manufacturing model. Whether Europe is ready for that new center of gravity is the real question behind the €2.05 billion price tag.


