Shield AI’s proposed $5.3 billion acquisition of Echodyne is not merely a defence-sector consolidation. It is a statement about where value is migrating within autonomous systems.
Artificial intelligence may make decisions, but autonomy remains constrained by what a system can detect, track and classify. By acquiring a compact-radar specialist, Shield is moving down the technology stack and securing greater control over the sensor inputs used by autonomous aircraft and counter-drone systems.
The strategic rationale is straightforward. The valuation is more difficult to explain.
What has been agreed
Under the definitive agreement, Shield will pay $4.8 billion at closing, with up to $500 million in additional consideration linked to performance. Closing is expected in early 2027, subject to regulatory approvals.
Shield is simultaneously raising $2.5 billion. This consists of a $1 billion Series H round at a $28.8 billion post-money valuation, $1 billion in structured equity from Blackstone-managed funds and $500 million in debt led by JPMorgan.
The financing mix matters. The headline valuation is not supported exclusively by conventional venture equity. Structured capital and debt introduce different repayment, return and risk characteristics.
The Echodyne purchase price represents approximately 18% of Shield’s stated post-money valuation. Neither company disclosed enough financial information to calculate a reliable revenue or earnings multiple.
A striking industry benchmark
One useful comparison is Axon’s acquisition of counter-drone company Dedrone. Axon’s annual filing valued the acquired 79.8% stake at approximately $391 million and its existing interest at $112 million, implying a total fair value of about $503 million.
Shield’s maximum Echodyne consideration is therefore about 10.5 times that amount.
This is not a like-for-like comparison. Dedrone is primarily associated with airspace awareness, software and counter-drone integration, while Echodyne owns a radar technology and manufacturing platform with broader applications. Even so, the gap demonstrates the premium Shield is placing on proprietary sensing hardware.
Shield’s $28.8 billion valuation also equals roughly 47% of Anduril’s reported $61 billion valuation following its $5 billion Series H. Anduril has followed a similar integration strategy, acquiring technologies across sensors, command systems and effectors.
The industry direction is clear: leading defence-technology platforms increasingly want to control the entire detect, decide and act chain.
What Echodyne contributes
Echodyne’s electronically scanned array radars use its proprietary MESA architecture. The company says its systems are deployed across hundreds of security and counter-drone installations in more than 40 countries.
Its radar products are already integrated with remote weapon stations, lasers, high-power microwave systems and command platforms. The company’s newsroom also shows recent selections involving BAE Systems and Kongsberg, illustrating its position within a broader partner ecosystem.
Shield and Echodyne say they both expect triple-digit revenue growth. That is a forward-looking management claim, and no absolute revenue figures were provided.
Echodyne also received a contract with a ceiling of $250 million from the US military’s JIATF-401. A ceiling defines the maximum potential value, not guaranteed orders or recognised revenue.
Similarly, Echodyne’s new 86,350-square-foot facility is designed to support capacity of approximately 30,000 radars per year. Capacity should not be confused with current output, customer demand or delivered units.
The neutrality problem
The acquisition could improve integration between Echodyne radar and Shield’s Hivemind autonomy software. Tighter sensor-software coordination may reduce latency, improve tracking and support autonomous responses in communications-degraded environments.
But Echodyne’s value also comes from being used by multiple integrators. Those partners must now consider whether a strategically important sensor supplier remains neutral after becoming part of Shield.
Shield says Echodyne will retain its team and continue offering standalone products. The practical test will be whether competing autonomy, command-and-control and counter-drone providers receive equal access to hardware, interfaces, support and product roadmaps.
This is particularly important in defence procurement, where customers increasingly request modular and interoperable systems rather than dependence on a single prime contractor.
A bet that extends beyond defence
Compact radar also has civilian relevance for airports, critical infrastructure, public safety and future uncrewed-aircraft traffic management. Echodyne could give Shield a path into these markets, although defence integration is clearly the deal’s immediate centre of gravity.
Fresh independent LinkedIn and Reddit analysis of the exact transaction remains sparse. Most early amplification has come from the companies, investors and defence-technology community. The more useful industry debate concerns open integration, manufacturing scale and whether large contract ceilings become repeatable orders.
Shield is paying a substantial premium to own a critical part of the autonomy stack. The acquisition will look prescient if Echodyne becomes a widely adopted sensing standard while maintaining its partner ecosystem. It will look far more expensive if integration narrows that ecosystem or if projected production and revenue growth fail to materialise.

#Business
Next article
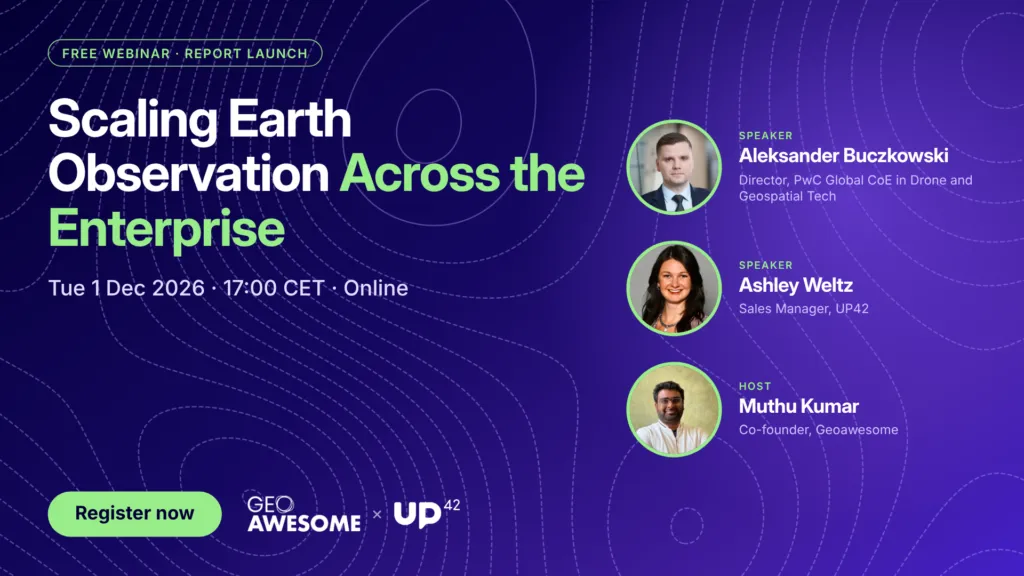
Many organisations have already shown that Earth observation can solve a real business problem. The harder question is what comes next. On 1 December, Geoawesome and UP42 launch a report that tries to answer it.
The second project is harder than the first
A first EO application usually succeeds because a small team pushes it through. Expanding it to other teams, regions and asset classes is different work. Without a shared model, each new use case rebuilds the same sourcing, contracting and integration process from the beginning.
The new report, Scaling Earth Observation Across the Enterprise, sets out a five-step framework for moving from isolated projects to an enterprise-wide geospatial operating model:
- Select the right opportunities for expansion
- Establish ownership and sustainable funding
- Simplify access to data
- Embed repeatable workflows into everyday operations
- Measure adoption and business value
Who is speaking
The launch session is hosted by Muthu Kumar, Co-founder of Geoawesome.
Aleksander Buczkowski, Director leading PwC’s Global Centre of Excellence in Drone and Geospatial Technologies, will share lessons from scaling geospatial solutions for enterprise clients, including governance, procurement, funding and integration with operational systems.
Ashley Weltz, Sales Manager at UP42, will draw on her work with enterprise customers and discuss how organisations can make data access, licensing and supplier management easier to scale.
What you take away
Practical guidance, tools and a 90-day action plan for turning a successful EO application into a lasting enterprise capability.
When and where
Tuesday 1 December 2026, 17:00 to 18:00 CET, online via Airmeet. Attendance is free.
Did you like this post? Read more and subscribe to our monthly newsletter!


